Portfolio Strategy for Self-Directed International Investors
A written investment strategy for your goals, holdings and cross-border constraints. One flat fee. Your assets stay at your own broker.

No obligation · No card details
§ 01 — Recognition · Who this is for You are probably here because…
This engagement is specific rather than general. It is built for self-directed, non-US-resident investors — from about €250k to €5m and beyond — facing a decision big enough that the structure matters more than the ticker. It serves both halves of an investing life: building the capital, and later living off it. If several of these describe you, the fit is likely good.
§ 02 — The deliverable · Investment Policy Statement Not a conversation. A document.
Most advice evaporates the moment the call ends. This engagement produces a written Investment Policy Statement — your personal investment mandate — that governs decisions long after the session. These are real pages from a real report.
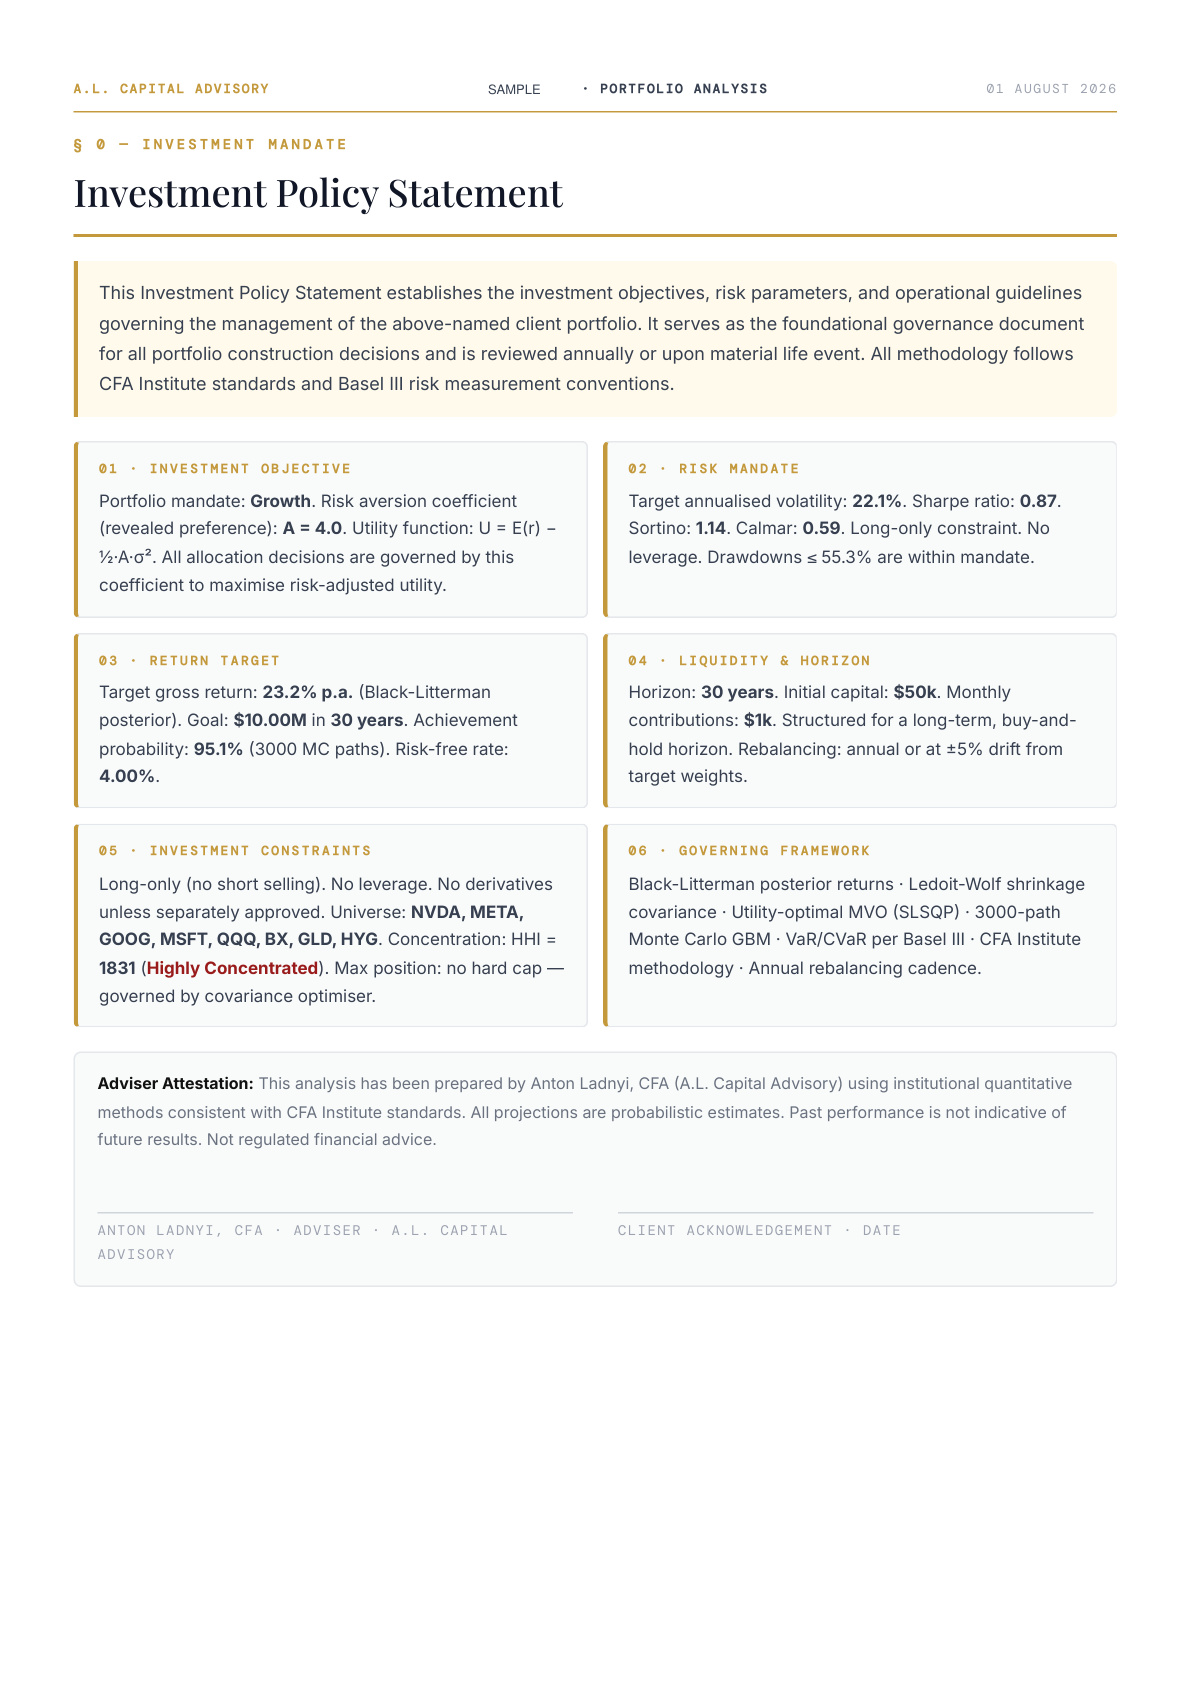
Objective, risk mandate, return target, constraints and the governing framework.
Illustrative sample. Figures describe this example and are not a projection of your results.
§ 02.1 — Contents of the engagement · What you receive One session. Eight outputs.
An Investment Policy Statement for a private investor is normally written by a CFA charterholder, a fee-only portfolio architect, or — for larger mandates — the private bank or family office managing the assets. It sets the strategic asset allocation, rebalancing thresholds, concentration limits and drawdown protocols in writing, so that the investor, not the adviser, has something to hold decisions to after the engagement ends.
The methodology behind it
Allocations are constructed using Black-Litterman with Ledoit-Wolf covariance shrinkage, rather than naive historical estimates that overfit to whichever decade happened to be in the sample. Forward outcomes are evaluated with Monte Carlo simulation across thousands of paths, and portfolio risk is attributed to individual holdings using Euler risk decomposition so that concentration is measured rather than assumed. Risk figures follow Basel III VaR/CVaR conventions.
The purpose of naming the methods is narrow: to establish that the recommendation is derived, reproducible and stress-tested rather than an opinion delivered confidently. The methods are the proof. What you buy is the mandate.
§ 03 — Precedent · Client engagements Selected mandates.
Documented decisions.
Real, paid engagements: two named examples and one anonymised at the client’s request. Explore the decisions documented, verify the published identities, and inspect the available redacted mandates. These are summaries of our work, not quotations from clients.
A thirty-year drawdown plan, pressure-tested before the first withdrawal.
- Explicit risk limits — built against drawdown, CVaR and volatility ceilings, not just a return target.
- 35% equity / 55% fixed income / 10% private credit — strategic allocation via policy-weight optimisation.
- Cross-border implementation — instrument domicile and distribution characteristics evaluated to reduce avoidable withholding exposure, subject to confirmation with local tax counsel.
- Withdrawal sustainability — stress-tested against a Monte Carlo ruin ceiling, with the safe withdrawal range mapped rather than assumed.
The honest probability behind the number — not just the number.
- A = 2.92 risk-aversion coefficient — placed in the Growth tier by behavioural calibration, not a generic questionnaire.
- 82% equity / 18% gold, five holdings — Black-Litterman posterior allocation across a global portfolio.
- UCITS correction — a non-UCITS gold holding swapped for a compliant equivalent.
- 30-year model, 10,000 Monte Carlo paths — the gap to his self-set target quantified, and exactly what closes it.
A ten-year growth target, priced as a probability — not a hope.
- A = 4.4 risk-aversion coefficient — calibrated by revealed-preference profiling, not a questionnaire.
- Nine-holding fixed strategic policy — 35% core S&P 500, the balance across emerging markets, Japan and satellites.
- 87.7% probability of reaching his target — quantified via a 10-year, 3,000-path Monte Carlo simulation.
- HHI concentration check — flagged at construction and monitored against the covariance risk model rather than left unmeasured.
On this evidence: these are real, paid engagements, published with each client’s consent; two are named and independently verifiable on LinkedIn, and the third is anonymised because that client did not consent to being named. The figures describe the analysis performed, not investment returns — a stated probability is a modelled estimate, not a forecast, and nothing here is a projection of your results. Most clients of this practice to date hold accumulation mandates, which is why two of the three shown are.
Put your situation in context.
A short fit call establishes whether this engagement suits the decision you face.
§ 04 — Accountability · Your portfolio architect Who is actually doing the work.

§ 05 — The alternatives · AUM adviser vs robo-advisor Three ways to solve this. Only one is this.
The main alternative to a percentage-of-assets wealth manager in Europe is a flat-fee, defined-scope engagement: you pay once for the portfolio architecture and the written mandate, and you keep executing the trades yourself at your own broker — rather than paying 1–2% of everything you own, every year, to a manager who takes custody.
A fair reading of that table: if you want someone to run the money for you, the first row is genuinely the right answer and you should take it. This engagement only makes sense if you intend to stay self-directed. Fee descriptions are general market characterisations, not quotes for any specific provider.
§ 06 — Process · How the engagement works Five steps. No surprises.
§ 07 — The fit callA clear next step.
Fifteen minutes, with Anton.
Discuss the decision you face and establish whether the €750 Strategic Session is a fit.
A scope and suitability conversation. No holdings upload or preparation required. Investment recommendations follow only within an agreed engagement.
Inspect the work before you book
Sample Strategic Session reportClient mandate: accumulationClient mandate: growthNothing is charged at booking. If you proceed, the €750 engagement is confirmed and invoiced by bank transfer.
Your details, then the decision you face.
Add broker or context optional
Free · 15 minutes · No card · Choose your time next
Privacy & data use
Your name, email and the details above are processed by A.L. Capital Advisory to respond to your enquiry and, if you proceed, deliver advisory services (GDPR Art. 6(1)(b)). Data retained for 3 years. Privacy Policy.
Your details are being sent. You can choose a time in the calendar.
No card was taken and none is needed. If the call confirms a fit, the €750 is invoiced by bank transfer afterwards — and the 30-day window after delivery means direct email access to Anton for anything that surfaces while you implement.
§ 08 — Questions · Portfolio strategy FAQ What people ask before booking.
Something not answered here? Ask it on the fit call — or email [email protected] and Anton will reply directly.